Use a backtest to study the rules. Use paper trading to check how those rules run as data arrives. A good score in either test does not prove that the plan will work with real money.
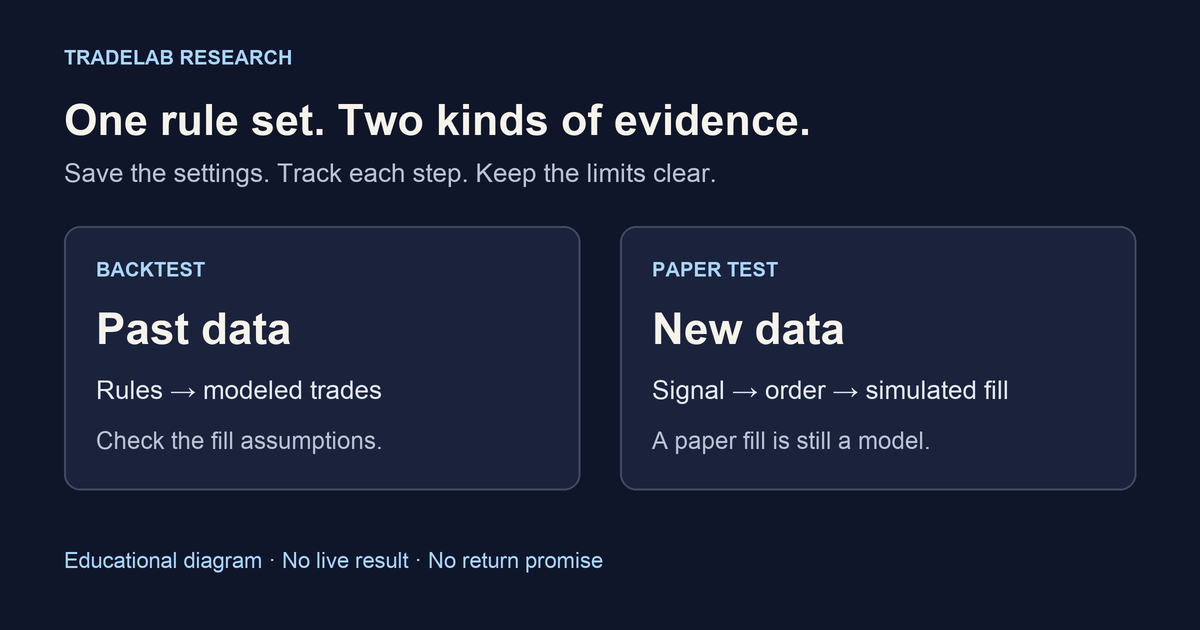
What is the difference?
| Check | Backtesting | Paper trading |
|---|---|---|
| Data | Past market data | New market data as it arrives |
| Main question | What would the rules have done in this sample? | What does the system do now, with these rules? |
| Useful record | Rules, dates, data, costs and trade list | Rules, signals, order states, simulated fills and errors |
| Key limit | The model makes assumptions about past fills. | Simulated fills do not prove live fill quality. |
A backtest needs a model for when orders fill. For example, TradingView explains how its broker emulator uses chart data and fill assumptions. Those are TradingView's rules, not a claim about TradeLab's test engine. Read the assumptions for the tool you use.
Which test comes first?
Start with clear trading rules. Then use the backtest validation checklist. Save one version before you start the next test. Otherwise, a rule change can get lost inside what looks like the same idea.
Save the handoff before the paper test
We suggest this short test record. It is a research method, not a promise that TradeLab saves every field for you. Keep notes for any field your tools do not save.
- Rules and version.Name the entry, exit, size and risk limits. Note the exact version.
- Data and clock.Save the symbols, data source, time frame, session and time zone.
- Test setup.Record the backtest dates, starting balance, cost model and order rules.
- Paper setup.Confirm the paper account and simulated balance. Keep API keys out of notes and screenshots.
- Review plan.Write what you want to check and when you will review it. Set a reason to pause, such as an unexplained order or missing data.
If you change a rule, give it a new version and keep the old result. Do not merge the two runs into one clean-looking record. The out-of-sample guide explains why using test results to change rules changes what the next test can show.
A signal is not a filled order
A signal means a rule called for an action. An order is the request sent to the broker. A fill records the amount executed. Check each step. Do not count one as proof of the next.
Alpaca's order guide lists states such as partially filled, filled, canceled and expired. Save the state, filled quantity and fill price when available. A pending cancel request is not a completed cancellation.
Made-up example · No return figures
Five signals. Three fully filled orders.
Suppose a paper run logs five signals. One fails your own size check before submission. Four orders are sent. Three fill in full. One expires with no fill.
- 5signals recorded
- 4orders submitted
- 3orders fully filled
The counts fit: five signals became four orders plus one blocked action. Four orders became three filled orders plus one unfilled expiry. This is a sample log, not TradeLab output.
It does not show three winning trades or three completed buy-and-sell pairs. No profit, loss or live result is given. If an order has a partial fill, record the filled amount too.
Paper trading still has blind spots
Alpaca simulates fills from current quotes. Its paper orders do not go to a live exchange. Its docs say the model leaves out market impact, price slip caused by delays and order queue position, among other factors. The simulation also does not check order size against the amount quoted as available. See Alpaca's paper-trading rules and limits.
A paper fill is useful evidence about that simulation. It is not proof that a real order of the same size would fill at that price. Keep the cost and slippage assumptions beside the result.
What if the tests do not match?
First, check what you are comparing. A long historical test and a short paper run cover different dates. Their total gains are not a fair test of whether the same rules ran. Start with the settings and a few events you can trace.
- Rules: Did both runs use the same version, size and order type?
- Data: Were the source, session and time zone the same? Was the signal based on a finished price bar?
- Orders: Which signals led to orders? Which orders were blocked, rejected, left open or partly filled?
- Limits: Did the result depend on a fill or cost assumption that the paper test uses differently?
Write down the gap before changing the idea. Mark a cause as unknown if the record cannot show it. Use the data-timing checklist if a signal seems to use a price or fact too early. If the sample is small, review trade count and market coverage rather than picking a fixed number of days as proof.
Where TradeLab fits
TradeLab brings rule building, historical backtests and paper trading into one research workflow. Review the rules and settings yourself. Use the record above to ask better questions; it does not describe an automatic audit or a test that certifies a strategy as ready for live money.
Sources and scope
We reviewed the linked Alpaca paper-trading and order docs and TradingView's broker-emulator docs on October 30, 2026. Provider rules can change. The test record and made-up counts are our teaching examples. They are not product results or trading advice.
Backtests and paper trades are models. They do not predict future results or copy all live trading risks. Live trading can lose money. It is a separate choice, not the next step by default. This guide is for learning, not financial advice or a call to trade.